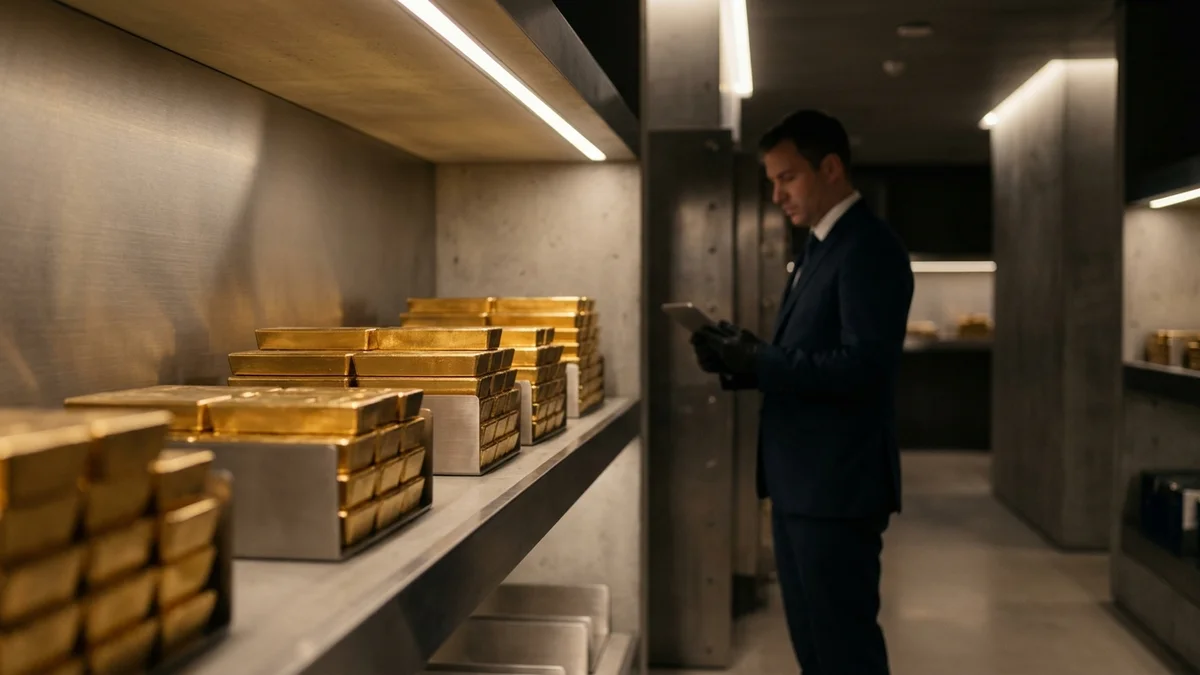
For more than half a century, international finance operated under an unquestioned assumption: the safest, most liquid, and undeniable asset on earth was United States sovereign debt (US Treasuries). Sovereign states, institutional reserve managers, and wealthy families systematically accumulated dollar reserves and debt notes issued by Washington as the ultimate hallmark of immediate liquidity and absolute solvency.
That consensus has quietly broken down. According to consolidated data and recent research published by the European Central Bank (ECB) and the World Gold Council, physical gold has officially overtaken US government debt as the single largest component of global foreign exchange reserves.
Gold has climbed to a historic share representing roughly 27% of all international reserves across the globe, while the portion held in US Treasuries has retreated to the neighborhood of 22%.
This realignment is not the result of short-term speculative hype on social media or retail momentum trading. It reflects a profound, calculated transition orchestrated by the world’s most sophisticated monetary authorities—with institutions across China, Poland, Turkey, and dozens of emerging economies accumulating physical metal to insulate their balance sheets from geopolitical friction, unilateral sanctions, and weaponized currency networks.
For private individual investors, this historic shift raises critical questions: what does this transformation mean for wealth preservation, and how should households construct an enduring safety net?
Key Takeaways: At a Glance
- •Historic Reserve Inversion: Gold has ascended to approximately 27% of central bank reserves, outpacing US Treasuries (22%) for the first time in modern economic history.
- •Zero Counterparty Risk: Unlike electronic sovereign paper and fiat obligations subject to asset freezes, gold is no government’s liability and requires no issuer promise to maintain intrinsic value.
- •Strategic Allocation vs. Speculation: Seasoned portfolio managers recommend maintaining a 3% to 7% allocation to gold as an insurance policy against systemic shocks, rather than chasing quick trading yields.
The Tipping Point: Why Central Banks Are Flocking to Gold
The structural catalyst that propelled gold past American sovereign paper originated in tectonic geopolitical events, notably the Western freeze of roughly $300 billion in Russian Central Bank reserves in 2022. That decision signaled to central bankers across developing nations and non-aligned economies that electronic assets held within foreign custodial jurisdictions carry significant counterparty and legal risks that physical gold will never possess.
As reported by Bloomberg News and the Financial Times, this realization has fueled three enduring forces in official reserve demand:
- Sanction and Freeze Immunity: Gold secured in domestic vaults cannot be confiscated by foreign courts, cut off from payment networks like SWIFT, or devalued by executive decrees of third-party nations.
- US Debt Trajectory and Currency Erosion: With US federal debt exceeding $35 trillion and chronic fiscal deficits persisting regardless of election cycles, monetary authorities are hedging against long-term structural dollar depreciation.
- Physical Repatriation of Sovereign Bars: In addition to purchasing new production, European and emerging nations have actively repatriated gold bars stored overseas, seeking uncompromised physical sovereignty over their reserves.
In Latin America, central banks have increasingly recognized the stabilizing role of gold, utilizing the metal to balance trade fluctuations and bolster external credibility during global financial turbulence.
What Does This Mean for Individual Portfolios?
Many individual investors make the mistake of evaluating gold through the same lens as stocks or real estate: expecting recurring dividends, fixed coupon payments, or exponential short-term capital appreciation.
Gold, however, does not generate operational cash flow—it pays no interest, generates no quarterly earnings, and cannot be valued via discounted cash flows. Its true economic utility lies in acting as an unbreachable insurance policy against monetary and systemic disruption.
When inflation erodes the purchasing power of local currencies and geopolitical stress spikes risk premiums, gold acts as a proven preserver of real purchasing power across generations.
The 3% to 7% Portfolio Rule
Modern portfolio theory and prudent asset allocators generally recommend that individuals maintain between 3% and 7% of their total net worth in gold or closely tracked vehicles.
Allocating more than 10% to 15% is typically inefficient for individuals still in the wealth accumulation phase, as the opportunity cost of bypassing productive, cash-flow-generating assets (such as dividend-growing equities, prime real estate, or high-yielding fixed income) remains substantial over multi-decade horizons.
Practical and Secure Ways to Gain Exposure
Today’s investor does not need to hide heavy bullion bars under floorboards—a practice fraught with security hazards, assay costs, and wide buy-sell spreads. Highly regulated and liquid vehicles offer seamless exposure:
- Physical Backed ETFs (e.g., GLD, IAU): Exchange-traded funds holding allocated bullion bars in verified vaults, offering institutional spreads and immediate liquidity during market trading hours.
- Direct Domestic ETFs: In regional exchanges (such as Latin America or Europe), regulated index funds track international bullion prices while automatically reflecting foreign currency movements.
- Global Royalty and Streaming Companies: Companies that finance mining projects in exchange for long-term rights to purchase physical metal at fixed, discounted rates, offering upside leverage without direct operating mine risks.
- Fractional Vaulting Platforms: Secure fintech services that allow retail investors to own verifiable fractional grams of vaulted physical bullion stored in Switzerland, Singapore, or North America.
Conclusion: The Resurgence of Monetary Realism
The fact that the world’s most disciplined central bankers have elevated physical gold above US debt securities offers an unmistakable lesson: the global monetary architecture is entering an era of multi-polar realism.
Insulating your personal balance sheet does not require predicting apocalyptic collapse; it simply requires adopting the same institutional foresight practiced by central banks—maintaining a durable anchor that answers to no single political entity.
Frequently Asked Questions
Why did gold surpass US Treasuries in global foreign reserves?
Because central banks worldwide systematically increased their purchases of physical bullion to mitigate geopolitical risks, asset freezes, and long-term purchasing power erosion caused by unprecedented US debt accumulation. Physical gold carries no counterparty liability.
Is buying physical bullion bars advisable for individual investors?
For most retail investors, storing substantial physical bullion at home is inefficient due to insurance requirements, retail dealer markups, and theft risks. Regulated exchange-traded funds (ETFs) or audited vaulting programs provide direct gold price exposure with instant liquidity and lower overhead.
What is the recommended portfolio allocation for gold?
Most financial planners and asset allocation frameworks advise between 3% and 7% of total investable assets. This allocation effectively reduces overall portfolio volatility during market dislocations without dampening the compounding power of productive assets.
🔗 Consulted Sources & References:
- European Central Bank (ECB) — Research on international reserve currency composition and sovereign reserve management
- World Gold Council (WGC) — Official central bank gold demand data, sovereign purchase statistics, and market trends
- Bloomberg News — Coverage of global de-dollarization trends and precious metal reserve allocations
- Financial Times — Analysis of sovereign foreign exchange reserve diversification and US debt dynamics
- Securities and Exchange Commission (SEC) — Prospectuses and regulatory disclosures for physical bullion exchange-traded products
Financial & Investment Disclaimer
The content in this article is for analytical, informational, and educational purposes only and should not be construed as financial, investment, or legal advice. All financial decisions should be evaluated according to your individual goals, horizon, and risk profile with certified financial advisors.